FBAR Requirements for Crypto Accounts Over $10,000: What You Need to Know
You hold a wallet on Binance or Kraken with $15,000 in Bitcoin. Do you need to file an extra form with the IRS? The answer is trickier than you might think. While the Foreign Bank and Financial Account Report (FBAR) generally requires US persons to report foreign financial accounts exceeding $10,000, cryptocurrency occupies a strange legal space right now. If you are a US person holding assets on a non-US exchange, understanding the current rules versus the likely future changes is critical to avoiding penalties.
The core rule remains simple: if you have a financial interest in or signature authority over one or more foreign financial accounts, and the aggregate value of those accounts exceeds $10,000 at any point during the calendar year, you must file FinCEN Form 114. However, for pure crypto holdings, the application of this rule has been suspended by recent guidance. This creates a split between what is legally required today and what experts recommend for safety.
Current Status: The FinCEN Notice 2020-2 Exemption
As of 2026, the governing document for this issue is FinCEN Notice 2020-2. Issed in late 2020, this notice clarified that a foreign account holding only virtual currency is not currently reportable on the FBAR. This means if your account on a foreign exchange like Binance contains solely Bitcoin, Ethereum, and other digital tokens, you technically do not need to include it in your FBAR filing right now.
This exemption applies specifically to "pure" crypto accounts. The regulation states that unless the account holds reportable assets besides virtual currency, it falls outside the standard definition of a foreign financial account for FBAR purposes. For most retail investors using centralized exchanges who keep their funds in crypto pairs, this provides a temporary reprieve from the annual filing burden.
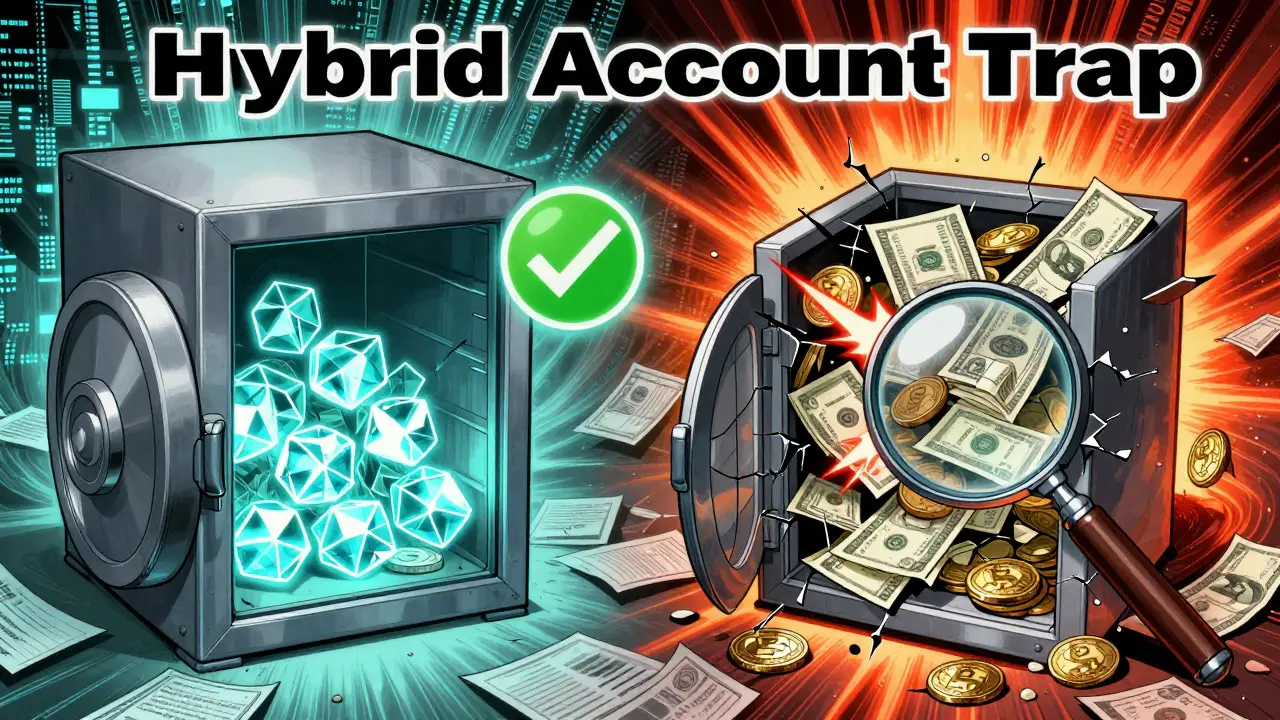
The Hybrid Account Trap
Here is where many investors get caught off guard. The exemption disappears the moment you introduce traditional fiat currencies into the mix. If your foreign exchange account holds US Dollars, Euros, or British Pounds alongside your crypto, it becomes a "hybrid account." These accounts are fully reportable under standard FBAR rules immediately.
Consider a scenario: You withdraw profits from trading into your USD balance on a foreign platform. Even if that USD balance is small, if the total value of the account (crypto + fiat) exceeds $10,000, the entire account becomes subject to FBAR reporting. You cannot simply ignore the crypto portion because the fiat portion triggers the requirement. Many users assume that because they trade crypto, the whole account is exempt. That is a dangerous misconception.
| Account Type | Contents | FBAR Status (2026) | Risk Level |
|---|---|---|---|
| Pure Crypto | Only Virtual Currency (BTC, ETH, etc.) | Not Reportable (per FinCEN Notice 2020-2) | Low (current), High (future risk) |
| Hybrid | Crypto + Fiat (USD, EUR, GBP) | Reportable if >$10,000 | High |
| Traditional Bank | Fiat Currencies Only | Reportable if >$10,000 | Standard |
Conservative vs. Literal Compliance Strategies
Tax professionals are divided on how to handle the current gray area. Two main schools of thought dominate the advice given to clients.
The Conservative Approach: Many firms, including specialized crypto tax advisors, recommend reporting foreign crypto accounts even though it isn't strictly required yet. Why? Because FinCEN has explicitly stated its intention to change the rules. By filing now, you create a paper trail showing good faith compliance. If regulations change retroactively or include transitional periods, having already reported these accounts can mitigate penalty risks. Jordan Bass, a prominent voice in crypto tax strategy, advocates for this method, noting that the administrative cost of filing is low compared to the potential penalty for non-compliance later.
The Literal Approach: Other experts argue that since the law says "not reportable," you should follow the letter of the law. Filing unnecessary forms adds complexity and time. They recommend strict documentation of account contents to prove that no fiat currency was held, thereby justifying non-filing. This approach saves time but carries the risk that if the IRS decides to enforce retroactive reporting, you have no prior filings to show cooperation.
Calculating the ,000 Threshold in Volatile Markets
Determining if you cross the $10,000 threshold is straightforward for bank accounts but chaotic for crypto. The rule requires you to look at the maximum aggregate value of all your foreign accounts at any time during the calendar year. It is not an average; it is the peak.
If your portfolio hit $9,500 on January 1st and spiked to $12,000 on March 15th due to a market rally, you are reportable. You don't need to be over the limit on December 31st. You don't need to be over the limit on average. One single day above the line triggers the obligation. For volatile assets like crypto, this means you might trigger the requirement without ever intending to hold that much cash. Tracking daily balances in USD equivalents is essential. Most investors use specialized software to generate these reports, as manual tracking across multiple wallets and exchanges is prone to error.
Who Counts as a "US Person"?
Before worrying about the amount, you must confirm you are actually liable. FBAR requirements apply to "US persons." This includes:
- US Citizens, regardless of where they live.
- US Residents (Green Card holders).
- Individuals meeting the Substantial Presence Test.
If you live abroad but retain US citizenship, you are still on the hook. Many expats forget this until they receive a notice. Additionally, "signature authority" matters. If you are listed as an authorized signer on a family member's foreign crypto account, you may have reporting obligations even if you don't own the assets, provided the account meets the value threshold.
Future Outlook: When Will Rules Change?
The current exemption is widely viewed as temporary. The Treasury Department and FinCEN are working on broader digital asset frameworks. Industry consensus suggests that final regulations requiring FBAR reporting for all virtual currency accounts will be proposed within the next 1-2 years. Once enacted, there may be a transition period, but the direction is clear: full integration of crypto into existing banking secrecy laws.
Because of this impending change, maintaining detailed records of your foreign crypto holdings is prudent regardless of whether you file this year. Keep statements, transaction logs, and valuation snapshots. If the IRS audits your past years after new rules pass, having proof of your balances and account types will be your best defense against negligence claims.
Practical Steps for Compliance
If you decide to file, or if you have hybrid accounts, here is how the process works:
- Identify All Foreign Accounts: List every exchange, wallet service, or bank located outside the US. Note if they are purely crypto or mixed.
- Determine Peak Value: Calculate the maximum total value of all reportable accounts (hybrid + traditional banks) during the year.
- Gather Institution Details: You need the name, address, and account number for each institution. Some privacy-focused exchanges make this difficult; you may need to contact support to get their official mailing address for the form.
- File via BSA E-Filing: FBARs must be filed electronically through the FinCEN BSA E-Filing system. There is no paper option. The deadline is typically October 15 following the end of the tax year.
Penalties for failure to file can be steep. Intentional violations can result in fines up to 50% of the account balance at the time of violation. Non-intentional violations carry lower fines but still require substantial documentation to prove good faith. Given the low cost of filing compared to the high cost of penalties, the conservative approach often wins out for peace of mind.
Do I need to file FBAR if I only hold crypto in a self-custody wallet?
Generally, no. A self-custody wallet (like MetaMask or Ledger) is not considered a "financial account" maintained by a foreign financial institution. FBAR applies to accounts held at institutions like banks or exchanges. However, if you use a custodial service (where the company holds the keys), it may count as an account. Always consult a tax professional for specific custody structures.
What if my account value fluctuates around $10,000?
If the value exceeds $10,000 at any single point in time during the calendar year, you are reportable. It does not matter if it drops back down below the threshold later. You must track the peak value, not the year-end balance.
Can I file FBAR late without penalties?
Yes, if you qualify for the Streamlined Procedures. This allows US persons living abroad or those who were not previously compliant to file delinquent FBARs and tax returns with reduced or no penalties, provided the failure was non-willful. It is a complex process, so professional help is recommended.
Does FinCEN Notice 2020-2 mean I never have to report crypto?
No. The notice is temporary guidance, not permanent law. FinCEN has indicated plans to update regulations to include virtual currency. Until then, pure crypto accounts are exempt, but hybrid accounts are not. Expect rules to tighten in the coming years.
How do I find the address of a foreign crypto exchange for the form?
Check the "About Us" or "Legal" section of the exchange's website. If unavailable, email customer support and request the registered business address and jurisdiction. You need the physical location of the entity managing the account, not just the server location.
nic c
August 30, 2026 AT 03:52Oh, you think the current rules are a relief? Let me educate you on the sheer magnitude of bureaucratic labyrinthine complexity that is FinCEN Notice 2020-2. It is not an exemption; it is a temporary suspension of your right to exist without paperwork. The 'hybrid account trap' mentioned here is merely the tip of the iceberg in this ocean of regulatory ambiguity. If you have even a single cent of fiat currency sitting in that foreign exchange, you are no longer a crypto enthusiast but a fully reportable entity under the guise of banking secrecy laws. Most people fail to grasp that the 'maximum aggregate value' rule means if your portfolio spikes for a split second during a market rally, you are liable, regardless of whether you actually withdrew that money or not. It is a classic case of the law being written by people who have never touched a blockchain, creating a scenario where volatility itself becomes a compliance trigger. Do not be fooled by the 'pure crypto' label; the moment you interact with a centralized exchange that holds your keys, you are stepping into a jurisdictional gray zone that could swallow you whole. The conservative approach isn't just advice; it is survival instinct in a world where the IRS has its eyes on every digital token transaction. So yes, file the form, keep your receipts, and prepare for the inevitable tightening of the noose around the neck of decentralized finance.
Alan Hawkins
August 31, 2026 AT 02:14This breakdown really helped clarify the distinction between pure crypto and hybrid accounts. I had been holding off on filing because I assumed my Binance account was exempt since it was mostly BTC, but I realized I had a small USD balance from a recent withdrawal. Thanks for pointing out that the entire account becomes reportable once fiat is introduced. It’s good to know about the BSA E-Filing system as well; I didn’t realize there was no paper option anymore.
Steve Sulley
August 31, 2026 AT 20:50so whats the point of having a wallet if the govt still owns it? i mean sure fincen says its fine now but its all just words on wind until they change their mind again. typical american bureaucracy trying to crush freedom with red tape. i dont trust any of these "exemptions" they give us, its just a way to track us before they tax it harder later. lazy critics like nic c love to make it sound complicated but its really just the state wanting control over everything. dont let them fool you with their fancy legal terms.
Linda Jevne
September 1, 2026 AT 06:48The concept of 'signature authority' really struck me here. It highlights how deeply entangled our financial identities are with institutional oversight, even in the realm of supposedly decentralized assets. It makes one wonder if the very definition of 'ownership' is shifting from individual autonomy to collective accountability. The idea that a spike in value can trigger reporting obligations feels almost poetic in its irony; the market's unpredictability becomes a legal liability rather than just a financial risk. It’s a fascinating tension between the fluid nature of digital currency and the rigid structure of traditional tax codes.
David Powell
September 1, 2026 AT 12:56How quaint. You’re still worried about filling out a form when the real issue is that you don’t understand the fundamental flaw in treating volatile digital assets with static banking regulations. The 'conservative approach' is just fear-mongering for people who can’t handle basic risk management. If you’re smart enough to trade crypto, you’re smart enough to read the actual text of FinCEN Notice 2020-2 instead of relying on generic advice columns. Don’t let the drama queens convince you that you need a lawyer for something as simple as checking a box.
Ellie Brooks
September 1, 2026 AT 19:06I am so glad I found this post because I was feeling really anxious about my Kraken account! It is such a relief to see that pure crypto holdings are technically exempt right now, but I think I might go with the conservative route just to sleep better at night. The part about tracking the peak value really made sense to me, especially since my portfolio swings so wildly with the market. It is great to have a clear list of practical steps to follow, and knowing that the deadline is October 15th gives me plenty of time to gather all my documents. Thank you for making such a complex topic feel manageable!
Sean Dalton
September 3, 2026 AT 16:05Typical American obsession with self-reporting. In Ireland, we simply trust the banks to do their job, or else we face the wrath of the Revenue Commissioners who are far more efficient at finding hidden assets than these US bureaucrats ever will be. Your 'gray area' is just a sign of administrative incompetence. Why should the burden of proof fall on the citizen? It is absurd that you need to calculate the maximum aggregate value of your own accounts while the institutions themselves hide behind privacy shields. A true nation would regulate the exchanges, not harass the individual holders. But then again, you Americans prefer to litigate your way through life rather than just following sensible, centralized governance.
Rajni Mathur
September 4, 2026 AT 20:09It is imperative to note that the distinction between custodial and non-custodial wallets is often misunderstood by the general public 📊💡. While the post suggests self-custody is generally exempt, one must exercise extreme caution regarding the definition of a 'foreign financial institution' as interpreted by future court rulings 😬. The current guidance is merely a snapshot in time, and relying on it without professional counsel is a high-risk strategy for any serious investor 🚀. Furthermore, the penalty structure for intentional non-compliance is disproportionately severe compared to the administrative cost of filing, which necessitates a thorough cost-benefit analysis before making a decision ✅. One should also consider the potential impact on international tax treaties if reporting requirements expand, as this could create double taxation scenarios that are currently unforeseen ⚖️. Therefore, maintaining a meticulous audit trail is not just prudent; it is essential for long-term financial security in this evolving landscape 🔍.